Gift Cards vs Physical Gifts: When the Card Is the Right Answer
There are gift lists where a voucher beats anything we ship, and a supplier who will not say which ones is not worth trusting on the rest. Here is the comparison, with thresholds you can test, what the reward evidence does and does not support, and which voucher rules bind your supplier rather than you.
We sell physical gifts, so check what follows against the sources. A card beats anything we ship on four kinds of list. An object beats a card on one thing — the only reason anyone prints a logo.
The four lists where a card wins
A team spread across borders. Inside the EU there is usually no customs step: a pallet to mainland France, Spain or Poland moves intra-Community — no declaration, commodity code or duty. The exceptions are the special fiscal territories — Canary Islands, Ceuta and Melilla, French overseas departments, Åland — outside the EU VAT territory, needing declarations and local import tax even from the same Member State. You still pay per-destination freight, a carrier window per country, failed addresses. Outside the customs union — Great Britain, Switzerland, Norway — add an EORI number, a commodity code per item, an Incoterms call: DDP, and you carry duty and unrecoverable import VAT, usually registering in the destination country; DAP, and your recipient is billed at the door. Northern Ireland is the exception inside the United Kingdom: under the Windsor Framework it stays in EU goods rules, so an EU parcel crosses no customs border. A code avoids all of it, if redeemable there.
Recipients whose tastes you cannot know — any tranche where you cannot name the person.
Small per-head values. A decoration run carries its own minimum, roughly 25 to 50 pieces per item: six country drops cost six freight charges, not six minimums. Add packing and carriage per parcel and, below about EUR 15 a head landed, the object is down to EUR 10 to EUR 12, which reads as cheap.
Last-minute needs. The clock starts at usable vector artwork, not your purchase order, and these are norms to confirm against your supplier's written lead time rather than guarantees: typically two to three working days to approval, ten to fifteen of production, two to five of transit per destination. Three to five weeks door to door, six to eight in the September-to-November peak when decorators are full. Only a flawless run lands inside three weeks, so at that notice a card is the only thing you can promise.
The evidence for non-cash rewards is thinner than either side admits
One laboratory study does most of the work here. Across four experiments with more than 320 participants, reviewed by the Incentive Research Foundation, the non-cash group significantly outperformed the cash group on goal attainment (Incentive Research Foundation, 2022). The reward was a USD 10 cinema gift card: evidence that a restricted, separate, enjoyable reward beats cash, which argues against cash bonuses, not against vouchers. Two limits: the design varied four attributes at once, so no clean comparison of reward type alone was run; and it was a paid-task lab study reviewed by a foundation funded by the incentives industry.
What a physical object adds on top
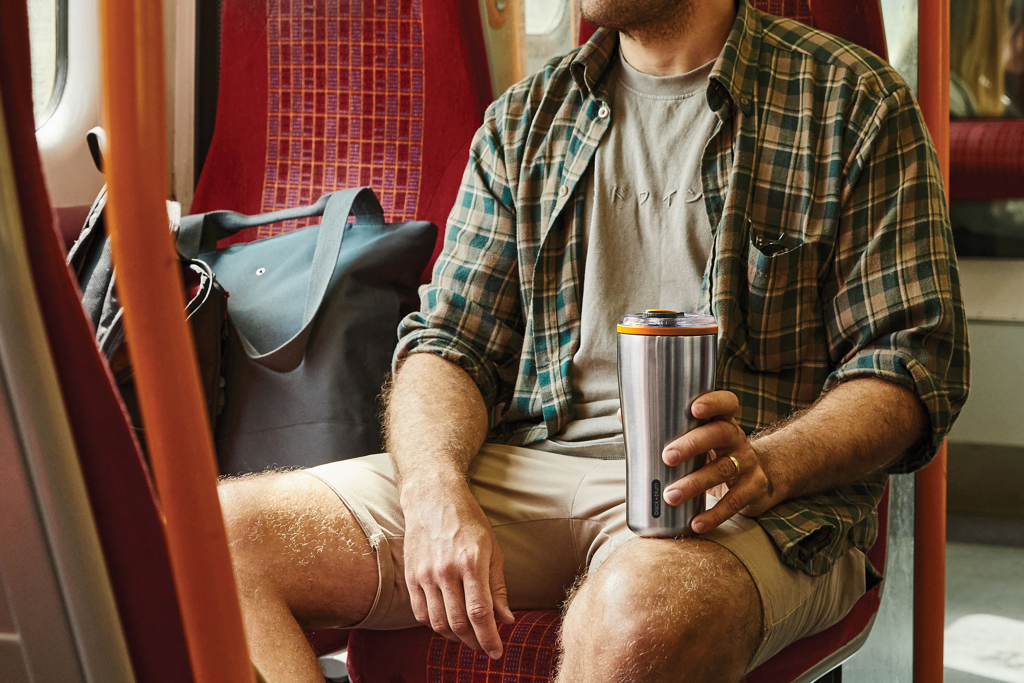
The object keeps working after the moment. ASI's release on its 2026 study, surveying nearly 5,000 consumers in the US, Canada, Mexico and Europe, reports 78% keep promotional products because they find them useful (ASI, 2026). ASI is the trade association measuring its own industry and the release carries no methodology, so read it as a global average and treat our preference for durable everyday categories as procurement reasoning, not something ASI measured. A Black+Blum insulated water bottle on a desk faces the same colleagues all year, a Black+Blum insulated travel tumbler strangers on a commute; a redeemed code faces one person, once.
The evidence is thin on both sides; the decision turns on the logistics and tax facts below, not on a study. To put a figure on the object half, our framework for measuring branded merchandise ROI builds the calculation from your own cost and retention numbers.
The VAT clock inside a voucher
Under Articles 30a, 30b and 73a of the VAT Directive (2006/112/EC), inserted by Council Directive (EU) 2016/1065 and applied from 1 January 2019, a single-purpose voucher — place of supply and VAT rate both fixed at issue — attracts VAT on every transfer including its issue; a multi-purpose voucher, only at redemption (European Commission, 2024). A single-retailer card does not qualify automatically: where its range spans more than one VAT rate, the VAT due is unknown at issue and the card is multi-purpose. That cost and cash-flow shape reaches you as the quoted price. The accounting duty sits on the taxable person transferring the voucher, under national implementing law — in the ordinary case whoever issues and distributes the cards, not you. Not a guarantee: national implementation differs, and what your invoice lets you deduct — and whether handing vouchers to staff creates a charge at your own end — is for your adviser, not something to assume away. Nor is a multi-purpose chain VAT-free end to end: distribution and promotion services along it are taxable normally.
There is no EU provision on vouchers never redeemed. The Commission's 2024 review found Member States "split on which specific guidance on their VAT treatment was provided", with six reporting concrete problems (European Commission, 2024). Only a minority raised problems and the rules were broadly judged clear, so this is an unsettled corner rather than a broken regime. It is also the source of every unsourced claim about breakage, the share of face value never redeemed. Treat unredeemed value as an open question, never as margin.
Questions for the voucher supplier, and one for your tax adviser
PSD2 (Directive (EU) 2015/2366), in national law since 13 January 2018, puts three limited-use instruments outside payment-services regulation under Article 3(k): those usable only on the issuer's premises or in a limited network under direct commercial agreement with a professional issuer; those for a very limited range of goods or services; and those valid in one Member State, provided at an undertaking's or public body's request, regulated by a national or regional public authority for specific social or tax purposes, and usable only for specific goods or services from suppliers under commercial agreement with the issuer — where most meal and culture vouchers sit (European Parliament and Council, 2015). Limited-network width is judged nationally, so one card can be inside the exclusion in one country and outside it in another. Nothing there binds you as a buyer; your supplier's position does. Member States must require a provider relying on either of the first two to notify its competent authority once payment transactions over the preceding twelve months exceed EUR 1 million (European Parliament and Council, 2015). Ask which of the three they rely on; if one of the first two, whether they have notified and when they last reviewed that answer; and have the contract oblige them to flag any change.
Tax at the recipient's end is national; Ireland illustrates. From 1 January 2025 an employer there may give each employee up to five small benefits a year tax-free, capped at EUR 1,500 across those five and never in cash; vouchers redeemable in whole or in part for cash do not qualify at all, and a benefit above the cap is taxable in full, not on the excess (Revenue Commissioners, 2025). That is Irish law, not an EU rule, and the only national scheme we checked at source. With no EU-wide employee-gift exemption, the question for your adviser is narrow: where each recipient sits, the ceiling there, and whether this card would fail that country's cash test.
Splitting the list, and the questions only the card half needs
Cards for the scattered, unknown and urgent; objects for the relationships you are building. A VINGA Miles thermos bottle engraved for forty people is a different purchase from 200 codes.
Scattered is not free either. There is no single European gift card: most retailer cards redeem only in their country of issue, and the ones that cross borders cover a named list of markets, not the EU, so check yours country by country. Open-loop prepaid cards vary by country in availability, currency and expiry. Either route, a several-market list means a multi-country platform or a separate purchase order and tax question per country. EUR 50 is also a different gift in Lisbon than in Stockholm: settle nominal value against local purchasing power. Expect an issuance or load fee, sometimes a per-recipient delivery fee, sometimes a platform subscription — ask for the all-in cost of delivering EUR 25 to 200 people in five countries as one number.
Contract for the two supplier questions above, plus three: where the card is redeemable and in what currency; the expiry period, and whether it differs by country; and what happens to unredeemed value at expiry and who keeps it. Issued codes are usually non-refundable and a code is a bearer instrument, so ask what a lost one costs to replace and keep the master list out of an open spreadsheet.
Then the addresses. Home delivery is personal-data processing: collect the address for this send only, say what it is for, offer an opt-out ending in a collection point. Whoever packs and ships is a processor, so you need a written agreement under Article 28 of the GDPR, a deletion date tied to the last confirmed parcel, and a bar on reusing the list. Codes to personal email raise the same question in smaller form.
The case we lose: 200 people across five countries with the UK in the list and three weeks to the date. All of it should go on cards, and we would say so before quoting rather than after, because a late object is worse than a code. The catalog prices the physical half; hand us the names you have decided should be physical and we will argue some back onto cards — contact us.